
 Life Insurance
 Health Insurance
 Pet Insurance
 Motor Insurance
 Travel Insurance
 Commercial Insurance


What Is a Child Education Plan?
A child education plan is a savings-cum-insurance product created specifically to help parents build a fund for their child's future education needs. You pay regular premiums over a fixed period of time, and at the end of the policy, you receive a lump sum payout that can be used for school fees, college fees, professional courses, or any other educational expense.
What makes a child education plan different from a regular savings plan is the insurance layer that comes with it. This means if something unfortunate happens to the parent during the policy period, the child does not lose out. The insurer takes over the remaining premium payments, the family receives the life cover amount, and the child continues to get a monthly payout to cover day-to-day costs. The plan stays active till the end of the term, and the full maturity benefit is still paid out.
In short, a child education plan makes sure your child's education goals are not left unfinished, whether you are there or not.
How Does a Child Education Plan Work?
01
When you purchase a child education plan, you choose a policy term and a sum assured that matches your child's future education goal. You then pay premiums at a frequency that suits you, monthly, half-yearly, yearly, or even as a one-time payment.
Once the policy term ends, the insurer pays out the maturity benefit as a lump sum. You can use this amount to pay for your child's college admission, tuition fees, or higher study abroad expenses.
Mr. Rajesh Sharma has a 4-year-old son. He wants to make sure his son has enough funds for college when he turns 18. Rajesh buys a child plan for 15 years with a sum assured of ?25 lakhs and starts paying yearly premiums.
If Rajesh passes away in the 8th year of the policy, the insurer immediately pays the death benefit to the family. All remaining premium payments are waived off. The plan continues to stay active for the remaining 7 years. On maturity, the full payout of ?25 lakhs is given to Rajesh's son or the nominee.
Why Should You Invest in a Child Education Plan?
Education costs in India are rising faster than general inflation. An engineering or medical degree that costs ?10 lakhs today could cost Rs.25–30 lakhs or more in 15 years. Relying only on your regular savings may not be enough to keep pace with this rise.
Here is why a child education plan is a smart choice for parents:
Builds a Dedicated Education Fund
A child plan keeps your savings separate and goal-oriented. You are not likely to dip into it for other expenses the way you might with a regular savings account.
Life Cover for the Parent
The policy gives the parents life insurance coverage throughout the policy term. This ensures the family is not left without financial support if something unexpected happens.
Triple Benefit on Parents' Death
In the unfortunate event of the parents' death during the policy period, the child and family receive three benefits together: the life cover is paid immediately, all future premiums are waived off by the insurer, and the child gets a monthly income to meet everyday costs.
Inflation-Ready Planning
By starting early and letting your money grow over a long period, you are better prepared for the higher cost of education your child will face in the future.
Regular Savings Habit
Paying premiums regularly pushes you to save consistently, something that is hard to do without a committed plan.
Tax Savings
Premiums paid and maturity amounts received under child education plans come with tax benefits, reducing your overall tax liability.
Key Benefits of a Child Education Plan

Maturity Benefit
Once your policy completes its full term, you receive the maturity amount in a way that suits you. You can take it as a single lump sum or spread it across monthly, quarterly, half-yearly, or annual payments for up to 5 years after maturity. This gives you full control over how and when you use the money.

Tax Benefits
Premiums paid towards a child education plan are eligible for a deduction of up to ?1.5 lakhs per year under Section 80C of the Income Tax Act. Additionally, the maturity amount received is tax-free under Section 10(10D) for annual premiums up to ?2.5 lakhs, making these plans a tax-smart investment choice for parents.

Death Benefit
If the policyholder passes away while the policy is still active, the full life cover amount is paid to the nominee right away. This immediate payout helps the family take care of urgent expenses like rent, school fees, and daily living costs without any financial disruption.

Waiver of Premium Benefit
This is one of the most important features of a child education plan. On the death of the insured parent, the insurer covers all remaining premiums going forward. The family does not have to pay anything more, and the policy continues until it matures naturally.

Loyalty Additions and Wealth Boosters
For parents who choose a longer policy tenure, many child plans reward long-term commitment with extra additions to the fund. Typically, loyalty bonuses of around 0.5% are added from the end of the 6th policy year, and wealth boosters of around 3.25% are credited from the end of the 10th year onwards. This makes staying invested over a longer period even more rewarding.
Different Types of Child Education Plans Available
Depending on your risk appetite and financial goals, you can choose from three main types of child education plans:

Child ULIP (Unit Linked Insurance Plan)
Premiums are invested in market-linked funds like equity or debt. Returns depend on market performance.
Parents comfortable with some market risk for potentially higher returns

Capital Guarantee Plan
The principal amount invested is guaranteed to be returned, regardless of how the market performs.
Parents who want safety of capital along with some growth

Guaranteed Return Plan (Traditional Child Plan)
Returns are fixed and decided at the time of purchase. You know exactly what you will get at maturity.
Parents who prefer certainty and predictable planning
Each of these plan types comes with the standard insurance benefits like life cover and premium waiver. The main difference is how your money is invested and what kind of returns you can expect.
Key Features of a Child Education Plan at a Glance

Lump Sum Payout at Maturity
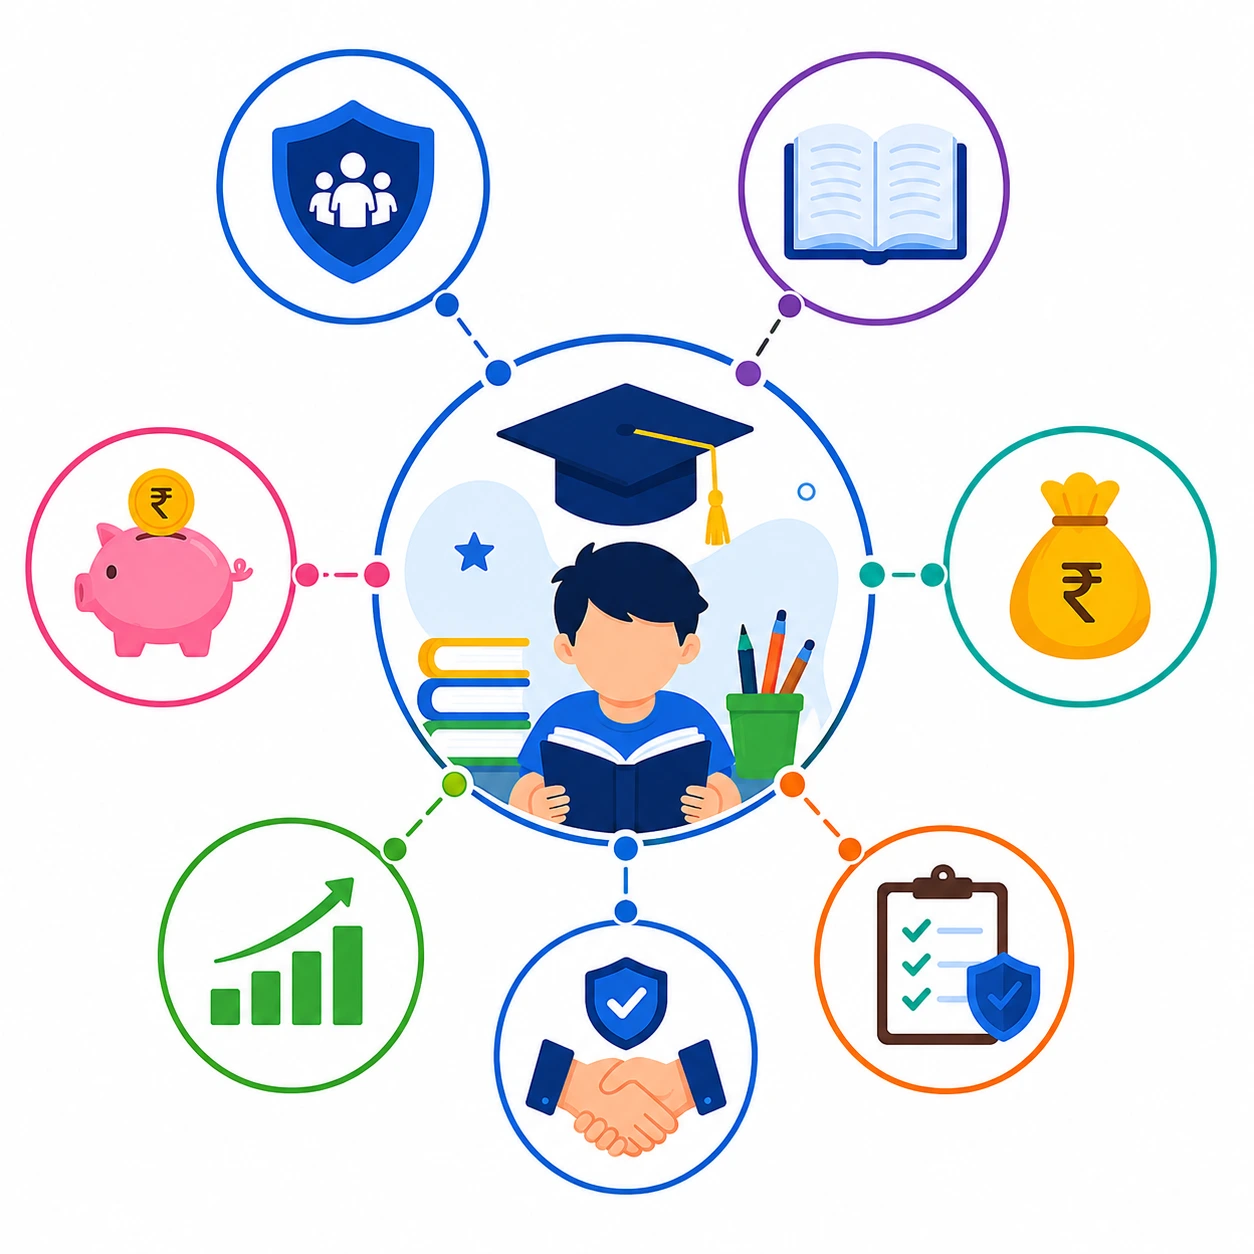
At the end of the policy term, the full maturity amount is paid directly to you. This corpus can be used to pay admission fees for colleges, fund a study abroad program, or even cover wedding expenses when the time comes.

Partial Withdrawal Option
You do not have to wait until the policy matures to access some of your funds. Most child education plans allow partial withdrawals after 5 years of the policy start date. This can be helpful for expenses that come up earlier, like school trips, competitive exam coaching, or school admission fees.

Life Cover Throughout the Policy
From the first day of the policy to the last, the parent has active life insurance coverage. If any unfortunate event happens during this period, the sum assured is paid to the nominee, making sure the child's financial future remains intact.
Tax Benefits on Child Education Plans
Child education plans offer tax advantages at two stages:

At the time of premium payment
The amount you pay as a premium every year is deductible from your taxable income up to a limit of ?1.5 lakhs per year. This reduces your overall tax burden while you are building the fund.

At the time of maturity or claim
The amount you receive at maturity or in the event of a claim is completely tax-free, provided your annual premium does not exceed ?2.5 lakhs. This applies to policies taken after 1st February 2021.
Note: Tax laws are subject to change. Please consult a tax advisor for the latest applicable rules.

Save Tax While Saving For Your Child
How Much Should You Invest in a Child Education Plan?

Investment Planning
The right investment amount depends on three main factors: your child's current age, the estimated cost of their target education, and the inflation rate that will push that cost higher over time.
A Practical Way to Approach This
Consider Meena, who has a 5-year-old daughter. She estimates that her daughter's college education will cost around ?35 lakhs in today's value. Accounting for education inflation of around 8% per year over 13 years, the actual cost when her daughter turns 18 could be close to ?65 lakhs. To reach this goal, Meena decides to invest ?15,000 every month in a child education plan, using the power of long-term compounding.
A general rule of thumb is to start with at least 15–20% of the estimated total education cost as your target savings, and then work backwards to figure out the monthly premium that fits your budget.
The earlier you start, the smaller the premium amount needed to build the same corpus. A 5-year head start can make a meaningful difference in the final fund size.
What Are the Advantages of Starting Early?
Planning for your child's education as early as possible gives you several practical advantages:

Compounding Works in Your Favour
The longer your money stays invested, the more it grows. Starting when your child is 2 or 3 years old instead of 8 or 10 years old can make a large difference to the final maturity amount with the same monthly premium.

Lower Premium for the Same Goal
An early start means you can spread the investment across more years, which brings down the monthly premium amount significantly without reducing the final payout.

More Time to Course-Correct
If your financial situation changes or education costs go up more than expected, starting early gives you more time to adjust your plan rather than rushing to make up for lost time.

Teaches Financial Discipline
Regular saving for a specific long-term goal sets a positive example for your child about how to plan and save for important goals in life.

Ready for Every Milestone
With the best child plan in place early on, you are financially ready for every milestone, from school admissions and coaching classes to graduation and postgraduate studies.
Documents Needed to Buy a Child Education Plan
Getting started with a child education plan is simple. Here is a list of the documents typically required:
| Document Category | Accepted Documents |
|---|---|
| Photo Identity Proof | Aadhaar Card, Passport, Voter ID, Driving License |
| Age Proof | Birth Certificate, Aadhaar Card, PAN Card, Passport, Voter ID, Driving License |
| Address Proof | Aadhaar Card, Voter ID, Electricity Bill, PAN Card, Driving License |
| Income Proof | Salary Slip, Form 16 |
| Bank Details | NEFT Details, Cancelled Cheque |
| Photograph | Recent Passport Size Photograph |
Having these documents ready before you apply helps speed up the process and ensures your policy gets issued without any delays.
How to Pick the Right Child Education Plan for Your Child?
With so many plans available in the market, choosing the right one can feel confusing. Here are a few things to keep in mind before you decide:
Look for the Triple Protection Feature
The best child education plan should offer all three: a life cover for the parent, a waiver of remaining premiums on the parent's death, and a monthly income for the child. If a plan offers all three together, it gives comprehensive protection.
Check the Partial Withdrawal Terms
Make sure the plan allows partial withdrawals after 5 years. Life comes with unexpected financial needs, and having access to a part of your fund before maturity can be a big relief.
Verify the Insurer's Claim Settlement Record
Always check the insurer's claim settlement ratio before buying. A high ratio means the company has a good track record of paying out claims. This matters most when your family needs it.
Review Premium Payment Flexibility
Look for a plan that offers flexible premium payment modes, monthly, quarterly, half-yearly, or annual, so you can choose what fits your income pattern best.
Match the Investment Style to Your Risk Level
If you are comfortable with market fluctuations and looking for higher growth, a ULIP child plan may suit you. If you prefer a fixed, predictable outcome, a traditional guaranteed return plan is a better match.
Start as Early as Possible
No matter which plan you choose, the most important thing is to start early. An early start means more time for growth and a lower financial burden each month.
How to Raise a Claim Under a Child Education Plan?
If the insured parent passes away during the policy term, the nominee or family member can file a claim by following these steps:
Step 1: Notify the Insurance Company
Reach out to the insurer's claims team as soon as possible after the incident. Share basic policy and incident details. You can also reach out to Okbima's claims support team for guided assistance throughout the process.
Step 2: Arrange All Required Documents
The following documents are generally needed:
- Completed claim form with accurate information
- Original policy document copy
- Valid identity proof of the nominee (Aadhaar, PAN, or Passport)
- Death certificate of the policyholder
- Medical records if the death was due to illness
- Police report or FIR in case of accidental death
Step 3: Submit Documents Within the Timeframe
Send all documents to the insurer within the stipulated period. Keep photocopies of everything you submit for your own records.
Step 4: Claim Review and Verification
The insurance company will review the documents and may ask for additional information if needed. They may also conduct their own assessment of the claim.
Step 5: Claim Settlement
Once the claim is approved, the insurer will process the payment as per the policy terms. The payout will be made to the registered nominee.
What Is Life Cover and Why Does It Matter in a Child Plan?
Life cover is the insurance component within a child education plan. It is the amount the insurer agrees to pay the nominee if the insured parent passes away during the policy period.
In the context of a child education plan, life cover is not just about the money; it is about making sure your child's future does not depend on your continued presence. Here is why it matters:

Financial Safety Net for the Child
The life cover payout gives the child immediate access to funds that can be used for education, living expenses, or any other financial need that arises after the parent's passing.

Peace of Mind for You
Knowing that your child is covered even in the worst-case scenario allows you to focus on your career, health, and family without constantly worrying about what would happen if something went wrong.

Affordable Protection
Life cover within a child plan is built into the premium you are already paying. It does not require a separate insurance purchase and is available at a relatively affordable cost when compared to the protection it provides over the long term.
Why Buy a Child Education Plan Through Okbima?
Okbima is an IRDAI-licensed insurance platform that helps over 2 lakh families compare and buy insurance products online. Here is why parents across India trust Okbima for their child's education plan:
Access to 50+ Top Insurance Partners
Okbima brings together plans from more than 50 of India's best child insurance companies, including HDFC Life, ICICI Prudential, SBI Life, Tata AIA, Bajaj Allianz Life, and more. You can compare plans side by side and pick the one that gives the best value for your budget.
100% Transparent Process
There are no hidden charges, no surprise deductions, and no confusing fine print. What you see on screen is what you get. Every feature, benefit, and premium amount is clearly shown before you make any payment.
Expert Guidance at No Extra Cost
Okbima has a team of insurance experts available to guide you before you buy. You can call, email, or request a callback and get honest, personalised advice based on your child's age, your income, and your education goal, free of cost.
Claim Assistance 24/7
Okbima's claim support team is available 24 hours a day, 7 days a week. During a difficult time, you should not have to navigate insurance paperwork alone. Okbima's team guides you step by step through the claims process.
Instant Policy Issuance
Once you select your plan and complete the payment, your policy document is sent directly to your registered email. No waiting, no branch visits, and no paperwork delays.
Renewal Reminders So Coverage Never Lapses
Okbima sends timely reminders before your premium due dates so that your policy always stays active. A lapsed policy can affect the benefits your child receives, and Okbima makes sure that never happens.
Competitive Premiums
By comparing plans across multiple insurers, Okbima ensures you are not paying more than you need to. Even a small saving on the annual premium adds up to a meaningful amount over a 15–20 year policy term.


